3 New Benefit Plan Ideas
3 New Benefit Plan Ideas:
Here are 3 affordable new benefit ideas for Human Resource Professionals looking to stand out from the pack:
1. Protection for student loan debt, in the event of a disability:
Separate from Group LTD, these plans specifically provide funds to pay student loans, in the event of a disability. Student Loan disability plans resonate with most employees, especially those with occupations that carry heavy student loan debt, such as physicians.
2. Employer-paid Critical Illness Protection for your Executives Class with amounts up to $100,000 per occurrence:
Critical Illnesses such as heart attack, stroke, and cancer, are some of the leading causes of disability, and can lead to substantial out-of-pocket medical expenses. Critical illness plans offered on a “voluntary” basis and only provide lower benefit amounts ($10,000 - $30,000 of coverage) and DON'T appeal to the highly compensated. However, an employer-paid plan with $100,000 or more of benefit, would appeal to an Executive class and have a positive financial impact.
3. Employer-paid Long-Term Care with Life Insurance protection for your Executive Class.
Long-term care bundled with Life insurance coverage is a product that can be offered on an employer-paid basis to an Executive carve-out, with group-like pricing, and on a guaranteed issue basis. These plans provide important asset protection during a long-term care claim, and life insurance benefit during death.
Long-term care plans with Life Insurance, is the new best way to offer long-term care protection since traditional coverage is no longer available on a group basis. Coverage provides funds for the cost of long-term care, which is generally not covered by other sources such as medical insurance.
With the average cost of care exceeding $12,000/month in many states, and an average claim lasting 3 years, the cost can quickly exceed $432,000. Without long-term care coverage, your executives would fund the cost of care out of pocket.
At time of death, these plans provide a death benefit minus any used funds for long-term care.
#employeebenefits #benchmarking #executivebenefits #somethingnew #partner #studentloan #criticalillness #longtermcare
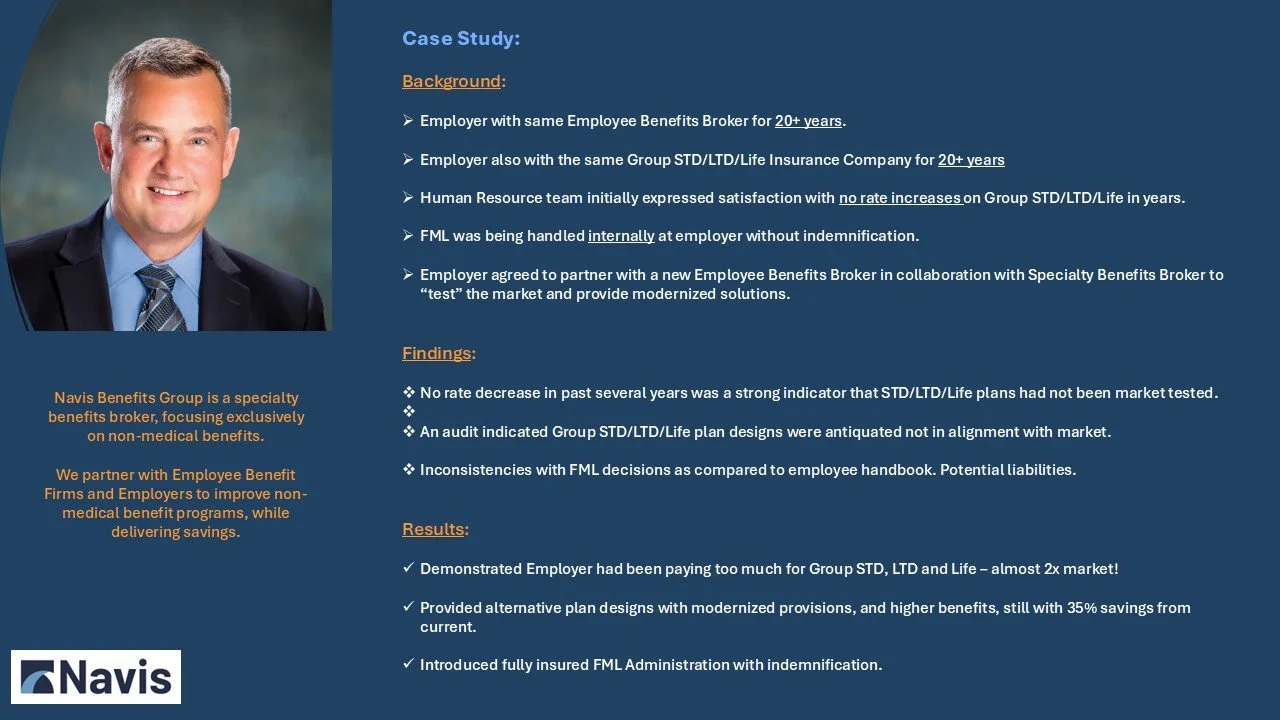
Case Study: How Partnering with Navis Generated Renewal Savings
Case Study: How Partnering with Navis Benefits Group Generated Renewal Savings
During this renewal season, consider partnering with Navis Benefits Group to achieve savings and plan improvements.
Case study shows how we partner with Employee Benefit Firms and Employers on non-medical benefits, to deliver savings and plan improvements.
Our mission at Navis Benefits Group is to give the non-medical benefits the focus, specialization, and shelf space necessary to strengthen the employee benefits package. We help Employers update their benefit plans to state of the art, competitive benefit programs. And deliver unrealized savings.
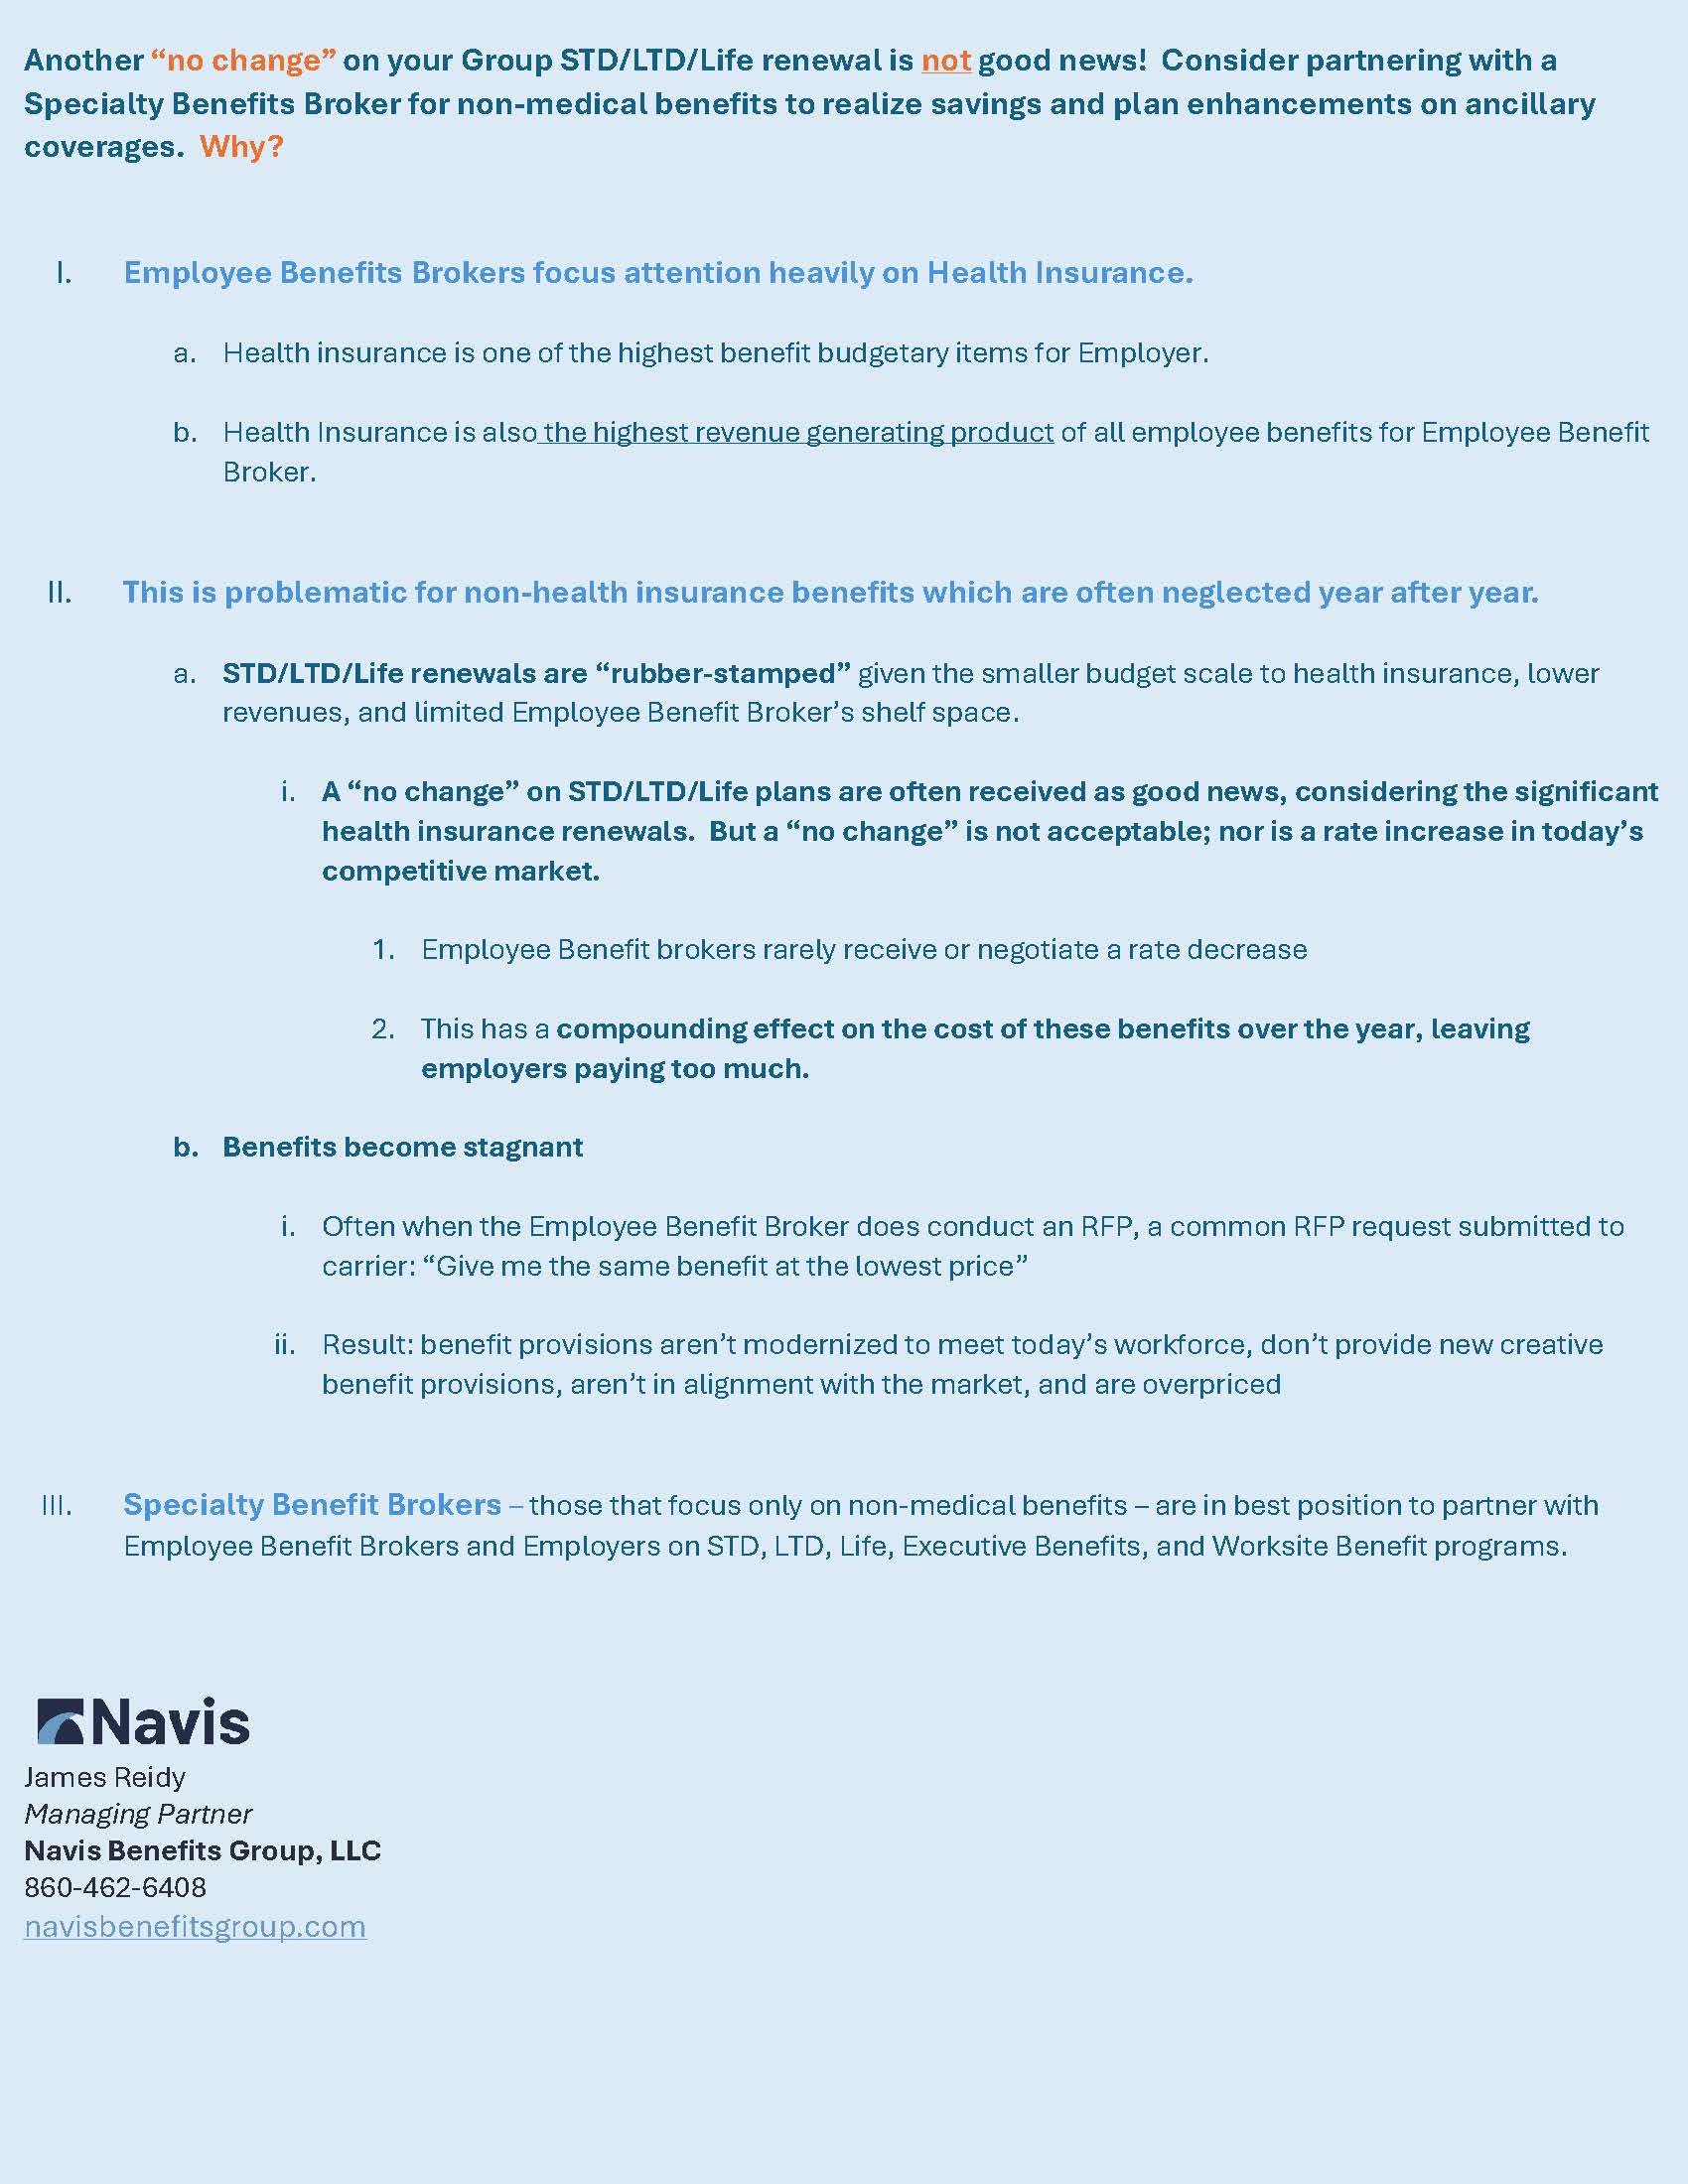
Another No-change Renewal? NOT Great News!
Another No-Change Renewal on Your Ancillary Benefits?
NOT Great News!
It’s employee benefit renewal season.
Many employers are receiving significant increasing sizeable rate increases on health insurance (again).
So, when an Employer receives a no change renewal, or even a slight increase on their Group STD/LTD/Life renewal, it’s welcomed as good news.
But it's not.
Refer to the visual to see why you should partner with a specialty benefits broker on your non-medical benefits.
If you haven't received a rate decrease, Navis Benefits Group can help.
Benefit Trend Alert: EDI vs. API
Benefit Trend Alert: EDI vs. API
When Employers and Employee Benefit Brokers think of upgrading an employee benefit program, they often think of new products, or richer benefits. Less thought is given to upgrading the process, which includes technology integration, streamlined administration, and the resulting employee experience.
While most Employers have moved away from “paper” enrollment and administration to leveraging technology, many Employers still operate in a traditional carrier connection environment, often referred to as an EDI connection. EDI connections still require manual intervention. Human Resource and Finance teams can spend manual hours keying benefit plan information into multiple systems. Every manual keystroke is an opportunity for an inaccuracy that could unintentionally derail the process and require considerable time and effort to resolve.
Leading HRIS Technology Providers and Insurance Carriers now leverage API connections. API connections are cloud-based connections that synchronize systems in real time. API connections streamline the benefit administration process, from enrollment, to life event changes, billing, and even claims, by eliminating the need for manual intervention and human error, reducing Human Resources’ most time-consuming tasks. Embedded APIs connections within the HRIS/Benefit Admin System enable direct integration with insurance carriers. In today’s complex world of “absence or leave management” API connections can also help employers, insurance carriers, and claimants ensure a smoother, and more accurate experience.
Not all HRIS/Benefit Admin Systems, and not all Insurance Carriers, leverage API connections. It is common for one – but not both – to leverage API connections, rendering the “technology advantage” mute. For employers who leverage a state-of-the-art HRIS/Benefit Admin platform that leverages API connections, such as Workday, UKG, or ADP, Employers should maximize this advantage to ensure that the Insurance Carrier they partner with for benefits, also leverages API connections.
Human Resource Professionals should partner with a Benefit Broker to evaluate their HRIS and Carrier connections well in advance of the annual benefits renewal. And make the change to a carrier with imbedded API connections to maximize their HRIS/Ben Admin investment.
Reach out to Navis Benefits Group if you would like to learn more about API feeds and how they can help your business.

HR Professionals: Looking for a new employee benefit to offer this fall?
HR Professionals: Looking for a new employee benefit to offer this fall?
Have you considered adding Long-Term Care protection?
Popularity for LTC protection has grown significantly in recent years, in part due to some fantastic product enhancements. New, innovative hybrid Life/LTC products offer 2-in-1 protection, combining Permanent Life Insurance with Long-Term Care benefits.
Perhaps most importantly, these hybrid solutions provide value whether the insured experiences a long-term care event or ultimately utilizes the life insurance death benefit. Employees receive Permanent Life coverage with guaranteed rates, guaranteed issue underwriting, and coverage that remains portable into retirement at the same premium level. If an employee experiences a qualifying LTC event, policyholders can accelerate their death benefit to help pay for care at home, in assisted living, or in a skilled nursing facility.
Hybrid Life/LTC solutions provide employers with a flexible benefit that can be offered on an employer-paid, employee-paid, or shared-cost basis while helping employees protect retirement savings and accumulated assets.

What is Long-Term Care?
What is Long-Term Care?
Long-Term Care refers to the assistance someone requires when they can no longer independently perform two or more Activities of Daily Living (ADLs), such as bathing, dressing, eating, or transferring; or when suffering from a severe cognitive impairment such as Alzheimer's disease or dementia.
Approximately 50% of Americans are expected to require some form of Long-Term Care during their lifetime.
When most people hear "Long-Term Care," they immediately think of care in a nursing home. This is a common misconception. Care can certainly be provided in a nursing home, but it can also be provided in an assisted living facility—or more commonly in the home or residential setting.
Consider this example: a young adult suffers a shattered hip during a skiing accident and cannot bathe, dress, or transfer (get around) without assistance for over a year.
Many people assume these expenses will be covered by health insurance, disability insurance, or Medicare. In most cases, they are not.
While medical insurance may cover hospitalization and physical therapy, it generally does not cover assistance with bathing, dressing, mobility, or supervision.
This leaves the cost of care to be self-insured or funded through personal savings, income, retirement accounts, or other assets. With costs averaging over $144,000 for one year of care in the Northeast, and care often needed for over 3 years, the financial impact can be crippling.
Understanding Long-Term Care is becoming increasingly important for Employers looking to expand their financial wellness offerings and differentiate their employee benefit programs.

"Can You Truly Unplug?
"Can You Truly Unplug?
For many HR professionals, time away doesn't always mean time off.
Questions about leave approvals, claim status, return-to-work dates, and employee eligibility can quickly follow you from the office to the beach.
Modern absence management solutions are designed to provide real-time visibility, employee self-service tools, integrated HRIS connectivity, and expert support to help keep things moving—even when you're away.
After all, employees aren't the only ones who deserve a smoother leave experience.
With over 29 years of experience, Navis Benefits Group helps employers evaluate absence management solutions designed to improve efficiency, support employees, and allow HR professionals to focus on what matters most.
#EmployeeBenefits #HR #LeaveManagement #WorkLifeBalance"

Are you managing disability and non-medical leaves in-house?
Are you managing disability and non-medical leaves in-house?
If so, have you considered who may be financially responsible if a leave determination is made incorrectly?
While many employers focus on improving administration and reducing HR workload, indemnification is often overlooked. Often, Employers and HR Staff are legally and financially liable for mistakes, inconsistencies, and oversights.
A fully insured leave solution can provide some protection.
BUT not all leave administration solutions provide the same level of protection. Some carriers may assume financial responsibility for certain administrative errors, while others may place more of that risk back on the employer.
Understanding the indemnification provisions within your absence management strategy can be just as important as understanding the employee experience itself.
With over 29 years of experience, Navis Benefits Group helps employers evaluate integrated absence management solutions and identify features that may help reduce organizational exposure while supporting employees throughout the leave process.
#EmployeeBenefits #AbsenceManagement #LeaveAdministration #RiskManagement #HR

API vs EDI: Is Your Benefit Technology Keeping Pace?
API vs. EDI: Is Your Benefits Technology Keeping Pace?
Platforms such as Workday, UKG, and ADP Workforce Now have helped employers streamline Human Resource operations and improve efficiency with API connections.
Yet disability, leave, and voluntary benefits are often still administered through EDI file feeds, discrepancy reports, and manual spreadsheets.
Modern API connections can help automate some of the most time-consuming Human Resource administrative tasks while improving data accuracy and employee experience.
From new hire onboarding and automated billing to evidence of insurability and claims management, employers can maximize the value of their HR technology investment while reducing administrative burden and reliance on manual processes with API connections.
With over 29 years of experience, Navis Benefits Group helps employers evaluate solutions designed to improve connectivity, increase efficiency, and simplify the administration of disability and absence programs.
#EmployeeBenefits #HRTechnology #API #BenefitsAdministration #LeaveManagement #HRIS #Workday #ADP #UKG

There are many reasons why we work hard. For survival, to pay for shelter, pay our bills, fund our child’s education, fund our hobbies, and because we love what we do.
The most important reason why we work hard is for our family.
This week, I will be stepping away from the job I love, to be with the family I love, and to celebrate my incredible wife’s birthday (it’s a big year!). I am more than excited to spend some downtime with my most important reasons.

Is leave administration becoming a headache for your HR team?
Is leave administration becoming a headache for your HR team?
Managing disability and medical leaves has become increasingly complex.
FMLA, state leave programs, STD, LTD, ADA accommodations, intermittent leave, and company-specific policies often overlap, creating administrative challenges for employers and HR professionals.
As leave laws continue to expand and evolve, many organizations find themselves spending more time managing processes and compliance requirements than supporting employees.
An integrated absence management solution can help coordinate leave programs, improve consistency, reduce administrative burden, and create a smoother experience for employees throughout the leave process.
Instead of managing multiple programs independently, employers can benefit from one coordinated approach that brings disability and non-medical leave administration together.
With over 29 years of experience, Navis Benefits Group helps employers evaluate absence management strategies and implement solutions designed to improve efficiency, support compliance efforts, and enhance the employee experience.

Most employers focus on the cost of leave. Fewer consider the cost of mismanaging leaves.
Most employers focus on the cost of leave. Fewer consider the cost of mismanaging leaves.
The employee’s leave itself is not the biggest expense. It’s the hidden costs that come from longer claim durations, delayed return-to-work outcomes, increased administrative workload, staffing disruptions, productivity losses, and compliance mistakes.
These impacts can extend far beyond wage replacement costs and affect multiple areas of an organization.
An effective absence management strategy can help improve coordination, support employees throughout the leave process, facilitate timely return-to-work outcomes, and reduce unnecessary organizational costs.
With over 29 years of experience, Navis Benefits Group helps employers evaluate absence management solutions to improve efficiency, reduce organizational risk, and support better outcomes for both employers and employees.

When was the last time a stress test was performed on your group LTD Plan?
When was the last time a stress test was performed on your group LTD Plan?
Employers routinely review medical plans, retirement benefits, and overall compensation strategies.
Yet LTD plans are often left unchanged for years.
Meanwhile, compensation structures, bonus incentives, taxes, and employee financial pressure continue to evolve.
A plan designed years ago may no longer align with how employees are compensated today — especially for highly compensated or incentive-based employees.
A simple income protection analysis can help identify whether current LTD coverage is still keeping pace.
With over 29 years of experience specializing in Supplemental IDI programs, Navis Benefits Group helps employers evaluate income protection strategies and address potential coverage gaps.

Does your compensation package include bonus or incentive pay?
Does your compensation package include bonuses or incentive pay?
Most Group LTD plans only protect base salary. In fact, bonus compensation is not covered by Group LTD plans 78% of the time.
Meanwhile, bonuses and incentive pay continue to represent a growing share of employee earnings — in some highly compensated professions, over 40% of total pay.
As pay structures evolve, many employers are surprised to learn how much employee income may fall outside traditional LTD coverage.
A simple income protection analysis can help determine whether current LTD coverage still aligns with how employees are paid today.
With over 29 years of experience specializing in Supplemental IDI programs, Navis Benefits Group helps employers evaluate income protection strategies and design solutions to address potential coverage gaps.

The “60% Myth”
Most employees think they understand their long-term disability (LTD) coverage. The reality is most don’t.
A Group LTD plan intended to replace “60%” of income can look very different once benefits are paid.
Why?
Enter plan maximums, compensation structures, and taxes into the equation, and the actual replacement percentage may be far lower than expected.
Highly compensated employees are bearing the burden of these factors even more than their colleagues.
With over 29 years of experience specializing in Supplemental IDI programs, Navis Benefits Group helps employers design and implement strategies to improve income protection and address potential coverage gaps.

If it’s not broken, don’t fix it!??
If it’s not broken, don’t fix it!??
Many Employers offer a Supplemental Disability (LTD/IDI) plan for their Executives and highly compensated employees. Once implemented, these plans often become stagnant, outdated, and over-priced.
Yes, it’s likely that the Plan Administrator is adding new Executives, terminating old, and exercising the annual benefit coverage increases due to salary increases. It’s not likely, however, that the plan will receive a thorough annual check-up unless the plan is designed and administered by a consultant specializing in Executive Benefit plans.
An Executive Benefit Specialist focuses on these benefits plans, isn’t hostage to the time and energy required by Health Insurance and has a deep understanding of Supplemental Disability programs.
An annual check-up performed by an Executive Benefit Specialist can help ensure the plan still meets the Employer’s financial wellness goals, offers the best pricing, appropriate plan maximum, aligns with the Group LTD plan, includes the best underwriting and Guarantee Issue maximums, and leverages the simplest administrative processes.
You’ve heard the old saying, “If it’s not broken, don’t fix it”. But by avoiding a thorough annual check-up or plan audit, the Supplemental LTD plan will in fact become broken.
Here are three examples:
1. Pricing:
a. The cost of Supplemental Disability plans has decreased significantly over the years. By doing nothing, over the course of just a few years, the Employer is overpaying for the plan – often 20-40% too much. An overhaul of an older plan – one even 5 years old – can deliver significant savings to an employer, despite an aging Executive group.
2. Administration:
a. Supplemental Disability plans normally require simplified underwriting with a short enrollment form. Plans today can be administered without requiring an enrollment form, if the plan is designed with underwriting correctly. Update to a new simplified onboarding process to save Human Resources time - and improve the onboarding experience for Executives.
3. Guarantee Issue Benefit Maximum:
a. A Supplemental Plan installed 5-10 years ago, may no longer adequately protect the Executives’ earnings. With increased earnings over the years, an Executive will eventually “hit” the Supplemental Plan benefit maximum. This means the Executive(s) will receive less than the target income replacement level. Increasing the plan maximum may be necessary.
By partnering with an Executive Disability Benefit Specialist, Employers can save premium, improve the onboarding process, save time, and update the Supplemental Disability Insurance plan to better align with the Employer’s goals.
Navis Benefits Group, LLC, specializes in Supplemental Long-Term Disability Insurance plans. Ask how Navis Benefits Group can help design, market, install, and administer a tailored Supplemental LTD plan.


Happy 4th Birthday, Navis Benefits Group!
Today we celebrate Navis Benefits Group’s 4th Birthday, and those that helped make this dream a reality!
I am humbled, and beyond grateful for the support and partnerships that helped make my dream a reality!
Thank you to the Employers and Employee Benefit Firms that chose to partner with Navis Benefits Group and placed their trust and confidence in my firm. And thank you to my carrier partners and vendors, for the support, tools, and extra effort you’ve given to my firm.
A very special thanks to my wife Christina, and my three boys (Dominic, Brayden, and Desmond), for the sacrifices and support you’ve given me along the way. You have been my inspiration and motivation to make Navis Benefits Group a well-respected, and successful firm. Navis Benefits Group is a reflection of you - and of your love and support!
After a successful 25-year career working for one of the industry’s best insurance carriers, making the move to start my own firm was a risky, and frightful proposition to say the least. But it was a dream that I had long wanted to pursue.
I am proud to report on this 4th Birthday, that Navis Benefits Group continues to exceed growth expectations. We’ve successfully helped Employers secure up to 50% savings on ancillary (Group STD/LTD/Life) benefit programs, installed high caliber Supplemental Disability Insurance Programs, Executive Benefit Plans, Long-Term Care Plans; helped Employer’s consolidate Voluntary Worksite Benefit plans; and implemented unique Employee Engagement and New Hire Orientation Platforms. Navis Benefits Group is in a strong position, and proud to celebrate this milestone achievement with our partners, customers, friends, and family.
I will always hold close to my heart, the support, encouragement, guidance and advice of my former colleagues, business partners, employee benefit consultants, human resource professionals, and friends. And most importantly, my family for taking the leap of faith, and for the sacrifices they made in the initial years to get things going!
With Sincere Thanks,
Jamie Reidy
Managing Partner & Founder
Navis Benefits Group is a “specialty benefits” Firm, focusing exclusively on non-medical employee benefits to include Group STD/LTD/Life Benefits, Executive Supplemental Disability Insurance, Voluntary Supplemental Disability Insurance, Executive Life Insurance, Long Term Care Insurance, Voluntary Worksite Benefits, New Hire Orientation Onboarding, and Benefits Enrollment/Communication solutions.

Haven’t Marketed Your Supplemental Disability Insurance Plan Lately?
Employers, do you offer a Supplemental Long-Term Disability Insurance plan as a benefit? If you do, congratulations! You are in a class of Employers that believes in offering a strong benefits package, to reward your key employees.
You’ve recognized that Group LTD alone can’t fully address the income requirements of your highly compensated employees. You understand risk diversification is an effective tool in your disability benefit strategy. And you offer a strong benefits program, to reward your most valued employees.
But when was the last time you completed a thorough review or marketing of your Supplemental Disability Insurance plan? You review your health insurance, STD/LTD/Life, and possibly your voluntary benefits, at least every other year. So, why not review and market your Supplemental Disability Insurance plan?
Yes, most Supplemental Disability plans employ a “non-can” rate structure. This means that the products rates are filed with the State(s) DOI and can’t be increased for any reason. In addition, the insurance carrier can’t cancel the individual contracts/policies which make up the benefit plan, for any reason. But, the Employer, and the Employees, are not bound to this “non-can” provision, and can terminate the coverage at any time.
Why would an Employer want to cancel, or replace, a Supplemental Disability Insurance plan? Some reasons include securing more competitive pricing, modernizing benefit plan provisions, negotiate a higher Guarantee Issue maximum, streamlining enrollment/new hire onboarding process, and leveraging improved administrative efficiencies.
Pricing – savings between 20% to 50% from current premium.
Increase benefit maximum/guarantee issue amount.
To ensure protection levels are keeping up with rising incomes and inflation.
Audit coverage:
Covered compensation: does your plan cover bonus compensation, commission, and K-1 earnings, in addition to base salary?
Definition of disability – does it align with your industry, and how your employees are paid? Is a loss of earnings required, or not?
Benchmark plan design against peers
Modernize benefit provisions, to include:
Mental/Nervous/Drug/Alcohol Protection for Full Benefit Duration
Removal of the 24-month limitation, so disabilities caused by mental/nervous/drug/alcohol are treated like “any other disability”
Long-term Care protection during the working years
Enhanced Paid Family Leave protection to care for family members
Serious Illness/Critical Illness protection helps with out-of-pocket expenses for disabilities resulting from a heart attack, cancer, or stroke.
NO Pre-existing condition limitation
Recovery Benefit continues benefit payments when an employee returns to work full-time following a disability but still experiences an income loss.
Important protection for employees that are paid commission or bonus income or are accounts receivable occupations (i.e. attorneys).
Process Improvements: onboard new eligible employees via census enrollment.
The days of collecting individual enrollment applications are over.
Guaranteed Standard Issue (GSI) vs. Guarantee Issue (GI)
GSI: 180 Day Active at Work requirement, which could result in an employee decline.
GI: Remove the 180 Day Active at Work requirement and replace it with a 1 Day Active at Work requirement, to align with Group STD/LTD/Life.
Navis Benefits Group specializes in Supplemental Disability Insurance Programs. With 29 years of specializing in Supplemental Disability Programs, including 25 years as an Executive Disability Insurance Consultant for the #1 provider of Supplemental Disability Insurance plans, Jamie is well positioned to assist you in the marketing of your current program. He’s worked with Fortune 500 Companies, Top AM 100 Law Firms, large Healthcare Organizations, Financial Institutions, and small professional employer organizations to achieve significant savings, process improvements, and benefit enhancements. Reach out to Navis Benefits Group, for a complete review of your Supplemental Disability Insurance plan.

The 80% Step-Up
The 80% Step-up: Upgrade Your Group LTD
Employers should consider updating their long-term disability program to provide 75%-80% replacement of total compensation, to better help employees avoid financial devastation during a disability.
Studies show that the American worker has been financially struggling for a long time.It is no secret. Even a “full paycheck” - 100% of base and bonus - is no longer enough to pay the bills.
Most Employers’ Group Long-Term Disability (LTD) Insurance plans only protect up to 60% of base salary. Replacing 60% of base salary was the “standard plan design”, once upon a time. Since the American worker cannot meet financial obligations with 100% of total compensation – protecting only 60% of base salary is no longer adequate.
Why not simply enhance the Group LTD plan? An employer could explore a Group LTD solution. However, Employers will find that despite the best efforts, a Group LTD plan that replaces 75% or 80% of total compensation does not exist.
In addition, addressing other shortfalls inherent to Group LTD plans, such as including total compensation, offering a higher benefit maximum to better protect highly compensated employees, and offering a tax-free benefit creates a high-risk LTD plan profile that would be extremely expensive. Group LTD carriers are conservative with offering these plan enhancements, especially when bundled. Never mind a plan design with 75% or 80% replacement of total compensation.
Many Fortune 500 companies have revised their long-term disability programs to include supplemental long-term disability insurance plans. These Supplemental plans can help protect up to 80% of base and bonus income when layered on top of Group LTD. Supplemental plans cannot protect 100% of income. Doing so would invite significant anti-selection according to the actuaries. But 80% is permissible and provides better protection than the “standard plan”.
Supplemental plans leverage non-can rates (fixed, state-filed rates) that cannot change for any reason, with group-like premiums. And since Supplemental claims experience has no negative impact on Group LTD claims experience or pricing, Supplemental plans in a sense serve as Group LTD’s version of “stop loss.”
Navis Benefits Group, LLC, specializes in Supplemental Long-Term Disability Insurance plans. Ask how Navis Benefits Group can help design, market, install, and administer a tailored Supplemental LTD plan